Capital accounts, quarterly estimated taxes, and an estate plan that needs to match the scale of what you've built — partnership brings a different order of planning complexity.
Most new partners come to us holding a distribution schedule full of holdbacks, PTET, and special distributions, and still can't answer two simple questions: what actually lands in my account each month, and how much do I set aside for quarterly taxes? We translate it into one page you can live by.
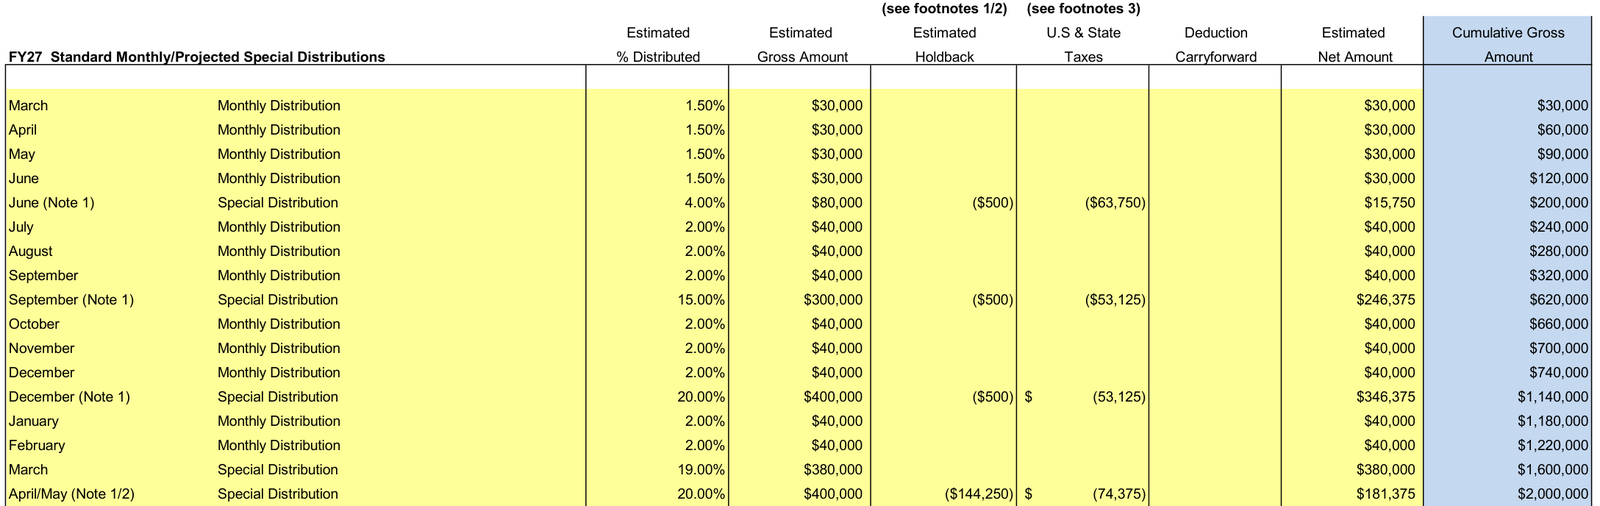
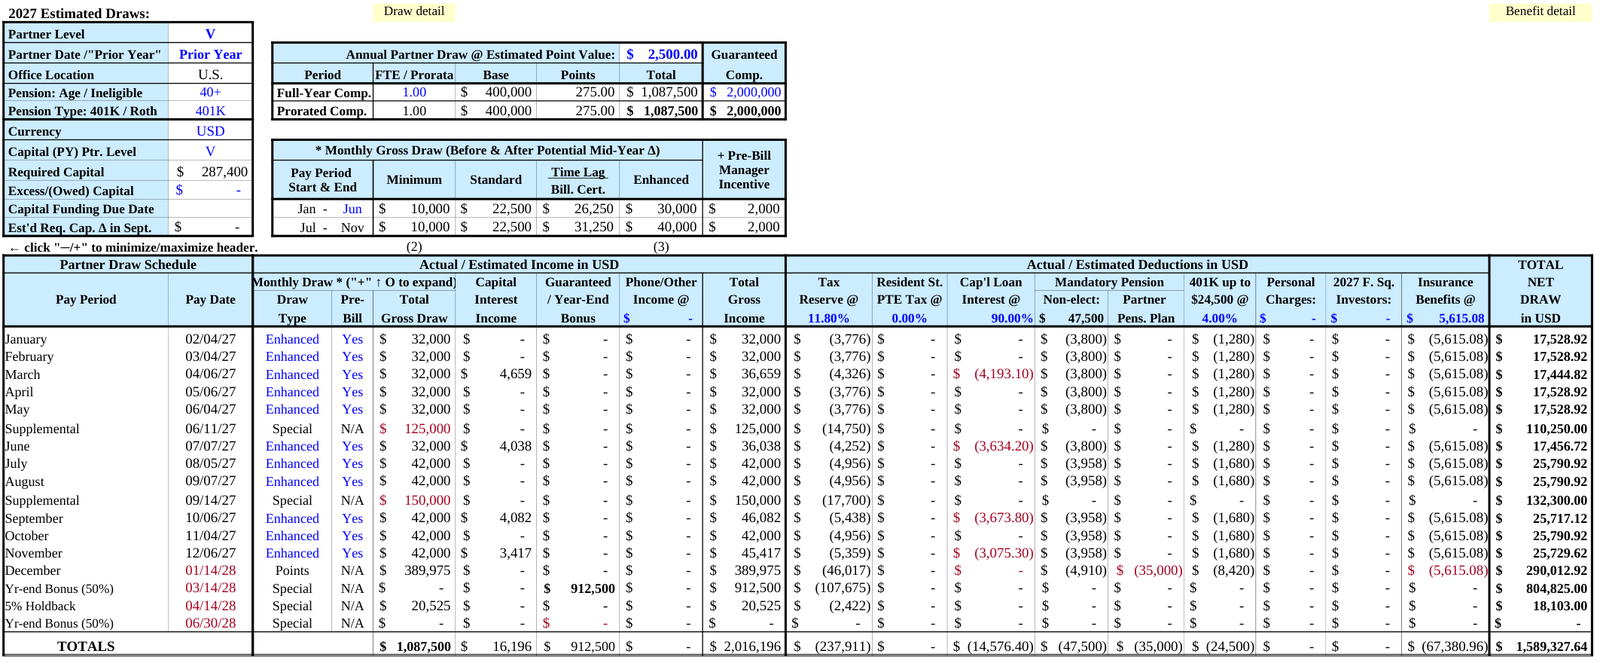
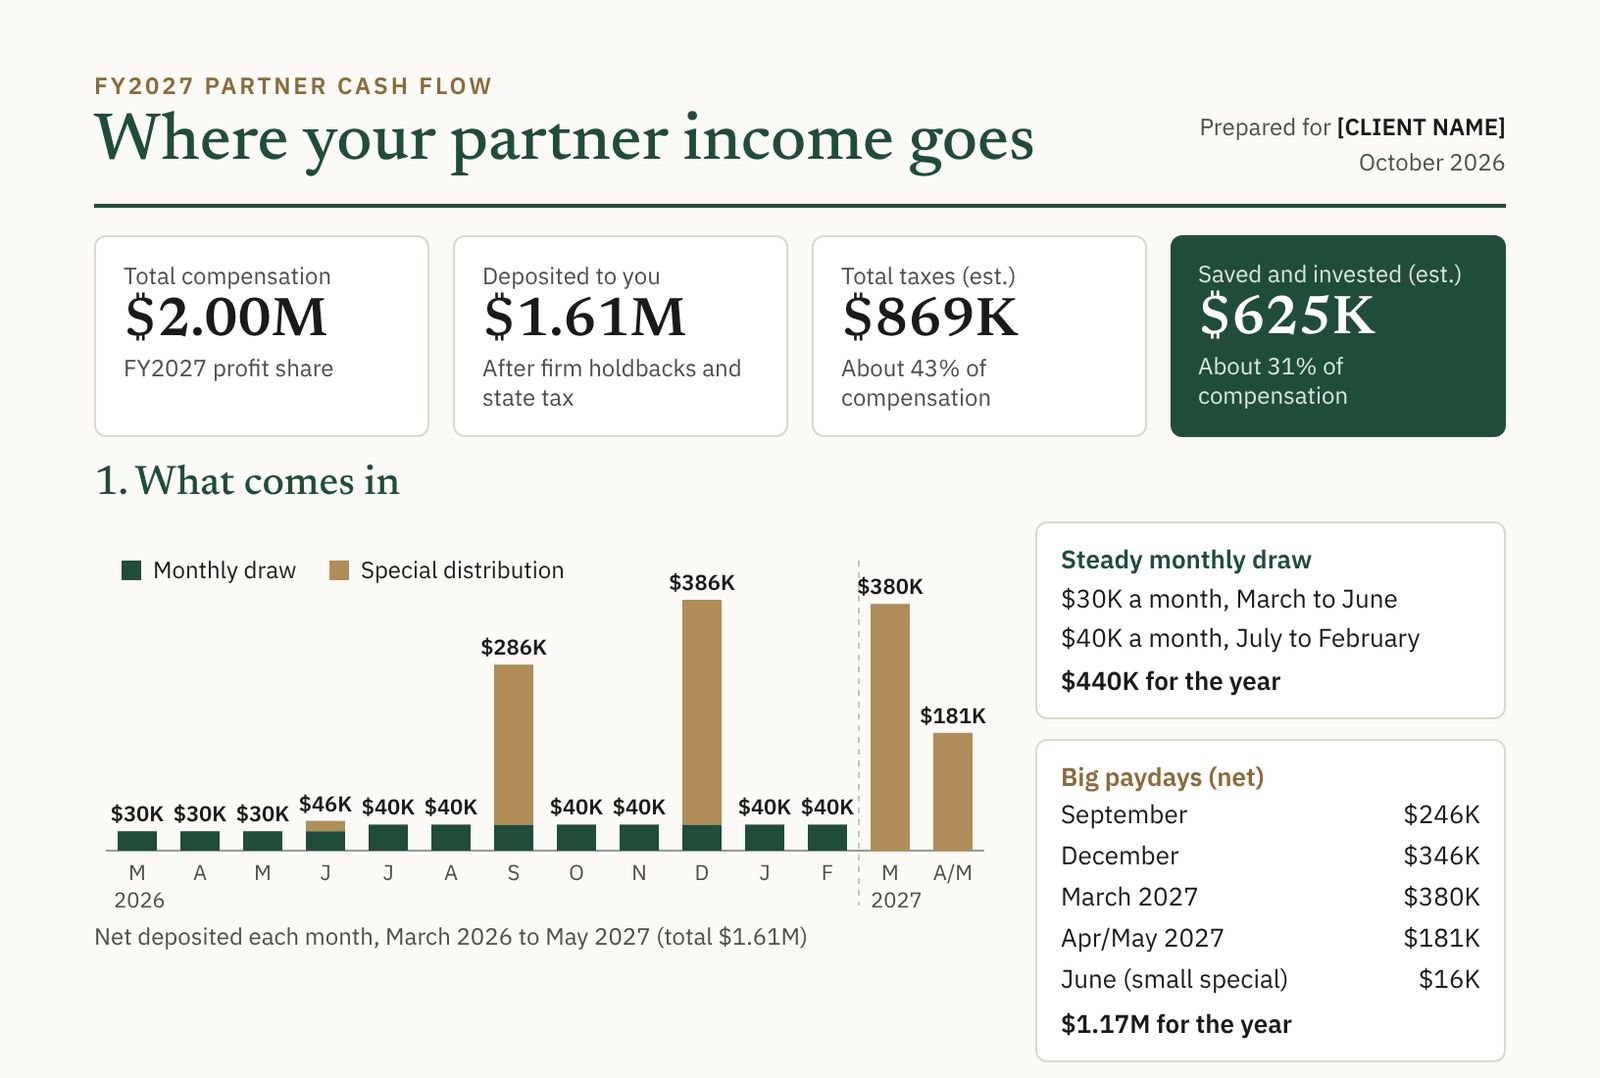
Illustrative example based on sample firm documents, with names and identifying details removed. Tax, spending and savings figures are hypothetical estimates for illustration only and are not tax advice or a guarantee of future results.
Reviewing your cash flow and compensation schedule so you can stay liquid when you need to without forfeiting long-term investment opportunities, along with your capital account structure and quarterly estimated tax strategy.
State tax exposure across jurisdictions, buy-sell and succession provisions, and estate and gifting strategy sized to your actual net worth. We also focus on coordinating your entire financial picture — many partners have accumulated a number of different accounts and products with multiple advisors over time. We act as your personal CFO to make sure every piece of your financial puzzle is working together.
Making partner changes more than your title. Here's what tends to catch new partners off guard:
We work directly with your CPA to model your actual state tax footprint.
Most estate plans need a real update once partnership income and capital accounts enter the picture.
A Cash Balance Plan is a type of defined benefit plan that lets high earners contribute well beyond standard 401(k) limits, often used by partnerships to accelerate retirement savings and reduce taxable income.
Rather than a regular paycheck, you typically receive periodic partner distributions throughout the year, with your actual taxable income reported on the K-1 you receive after year-end.
We look at financing options, timing, and how the buy-in fits into your broader cash flow and savings plan well before the check is due.
We estimate your annual tax liability early in the year and set up a quarterly payment schedule so you're not caught short at filing time.
Cash Balance Plan contributions, entity structuring, and timing of income and deductions are usually the biggest levers at this income level.
Often, yes — and it can open up additional retirement plan and tax planning options. Whether it makes sense depends on your firm's structure and your specific situation.
Often yes, with the right process in place — it usually comes down to pre-clearance and restricted lists rather than an outright ban.
Read more on the blog →Semi-annual check-ins, year-round access to your advisor, and all of your accounts aggregated in one place so you always know where things stand.
See the Client Experience →